Smaller teams, more buyers and a tilt towards work: what 2025 told us about exits in Learning & Work
Download Brighteye's M&A Report
Our M&A Report tracks 215 acquisitions of European Learning and work companies that took place in 2025. Here's our top takeaways...
One of the most persistent assumptions in the Learning & Work space is that exits are rare and that they only arrive for companies that have already reached real scale; build the platform first, and the buyers will come later.
The 2025 data paints a different picture.
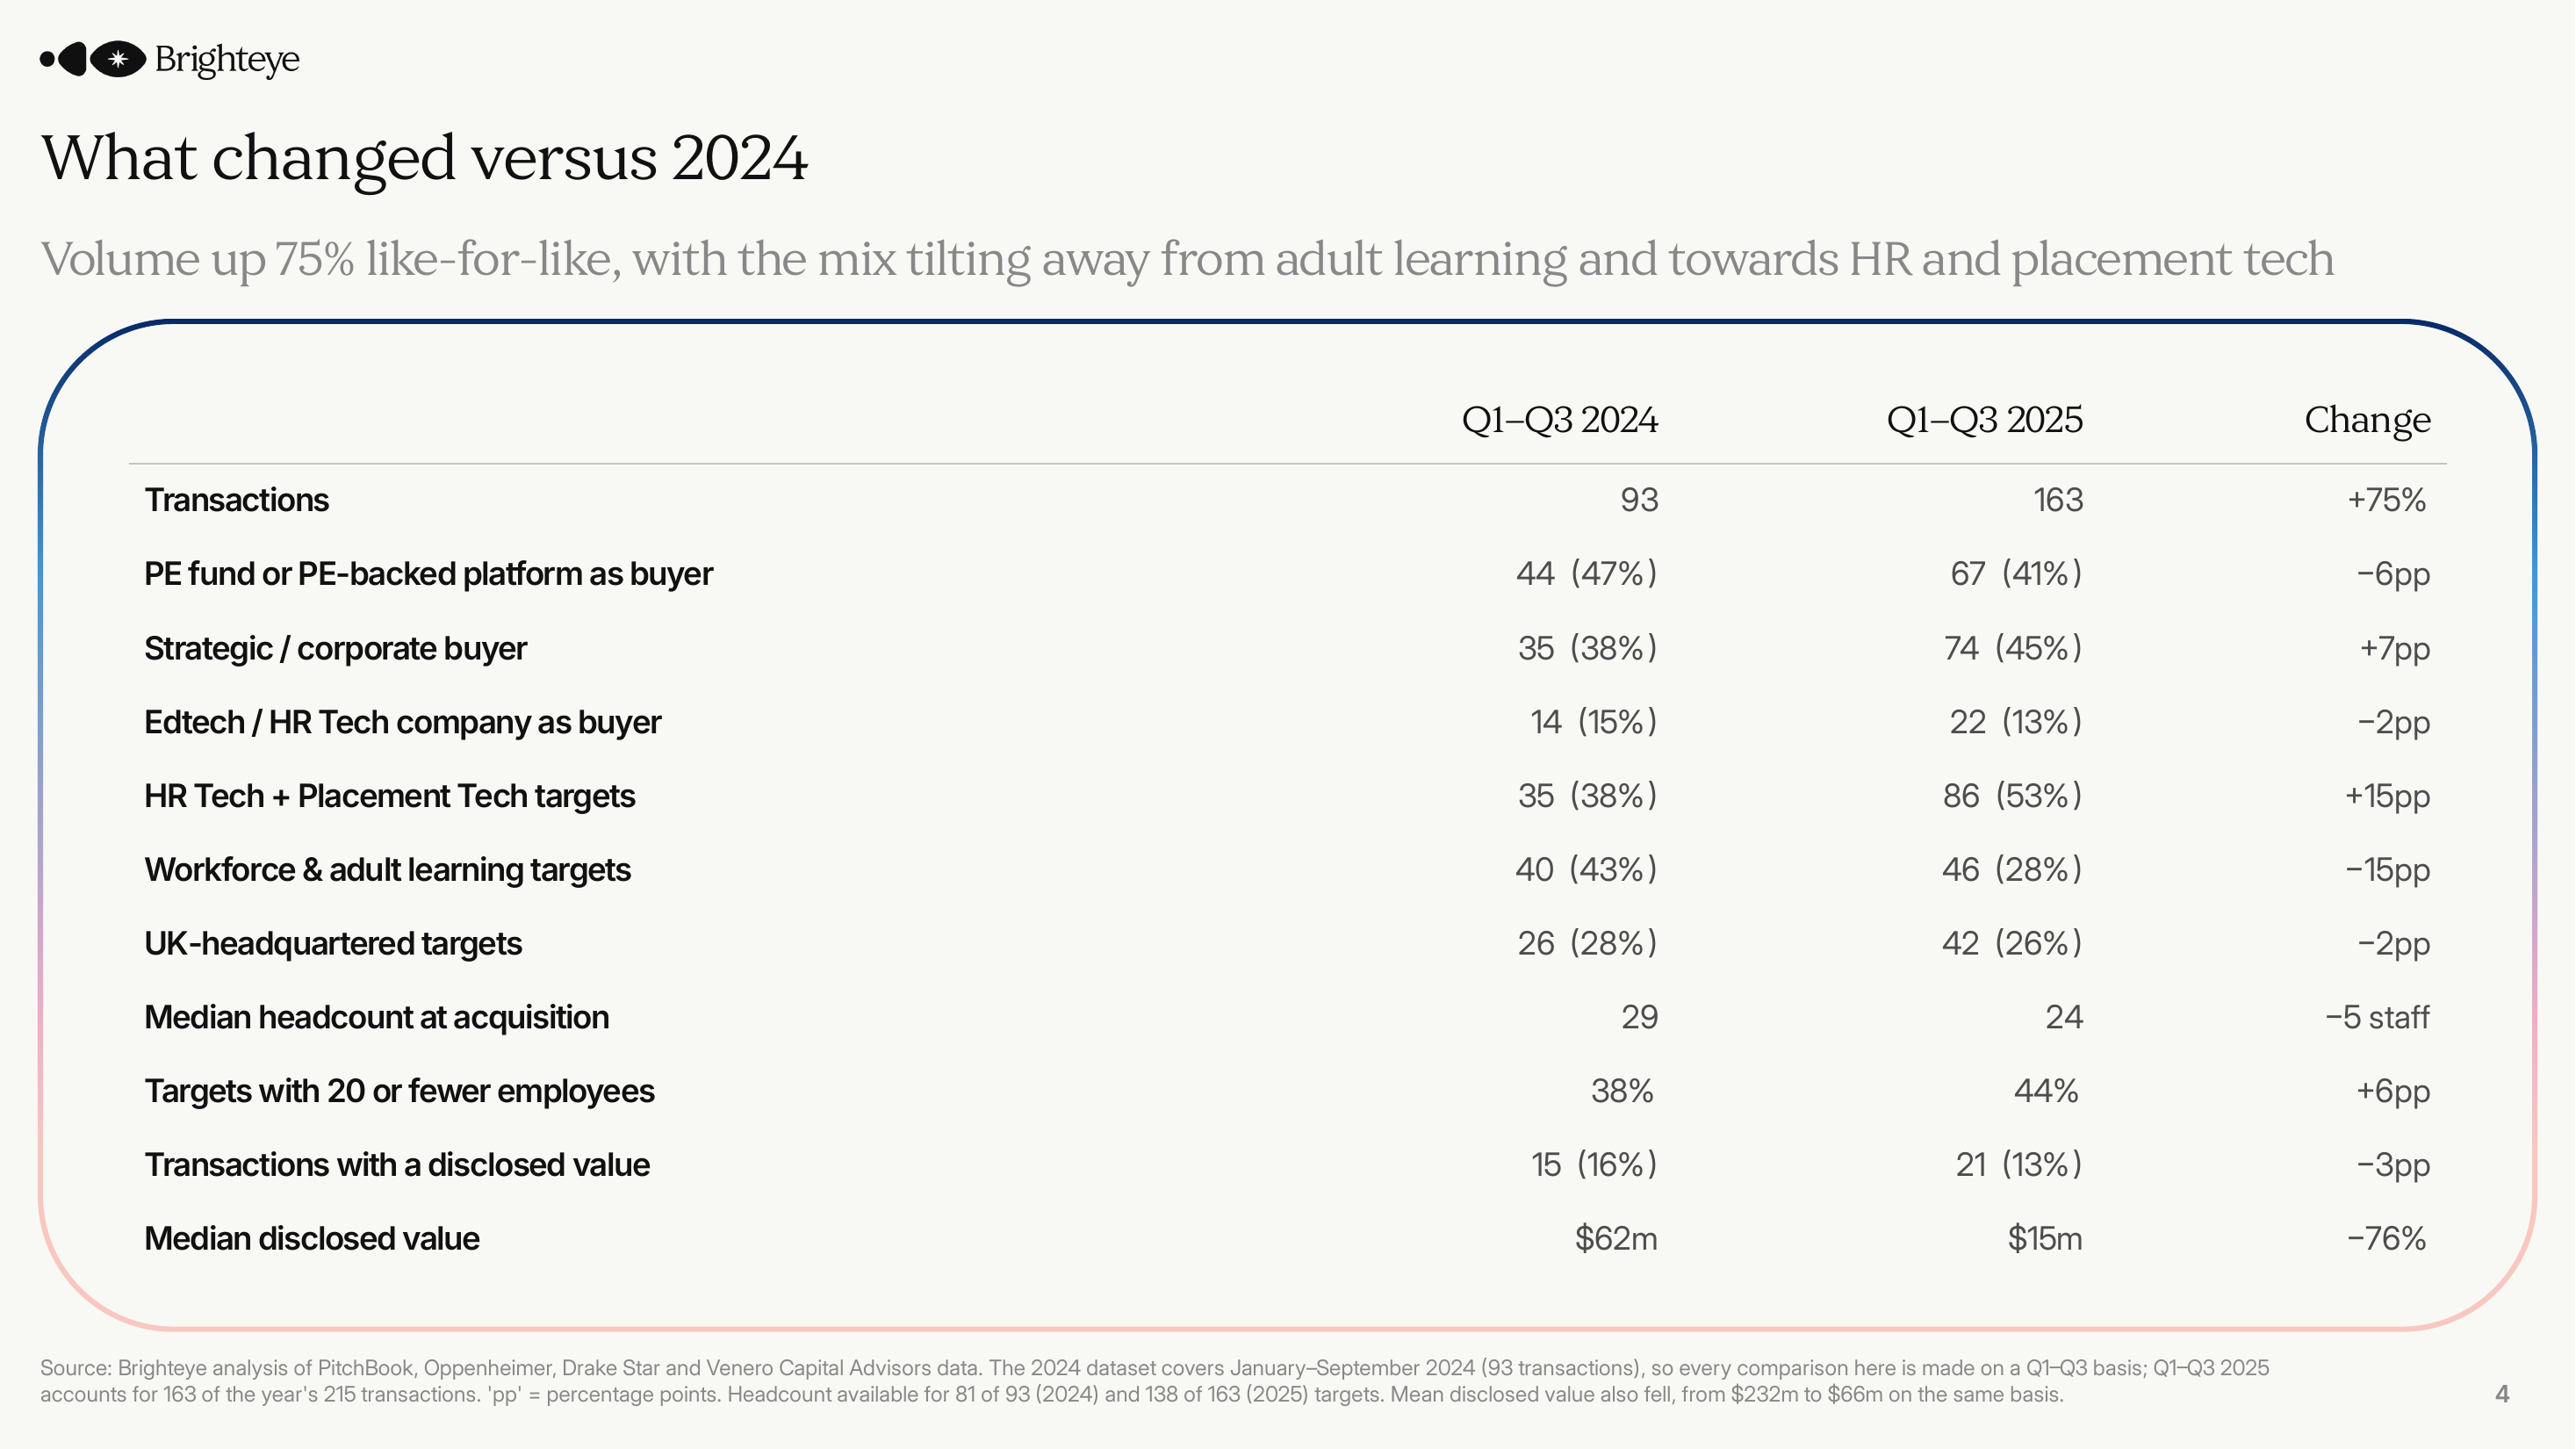
Across the year, we tracked 215 acquisitions of European Learning & Work companies. Compared like-for-like with the first nine months of 2024, deal volume was up 75%, from 93 transactions to 163. Deal flow was also steady all year, with no single quarter accounting for more than 28% of activity. But the headline number is the least interesting part of the story. The mix underneath it moved and that's where we'd suggest founders focus.
The bid sits on the work side
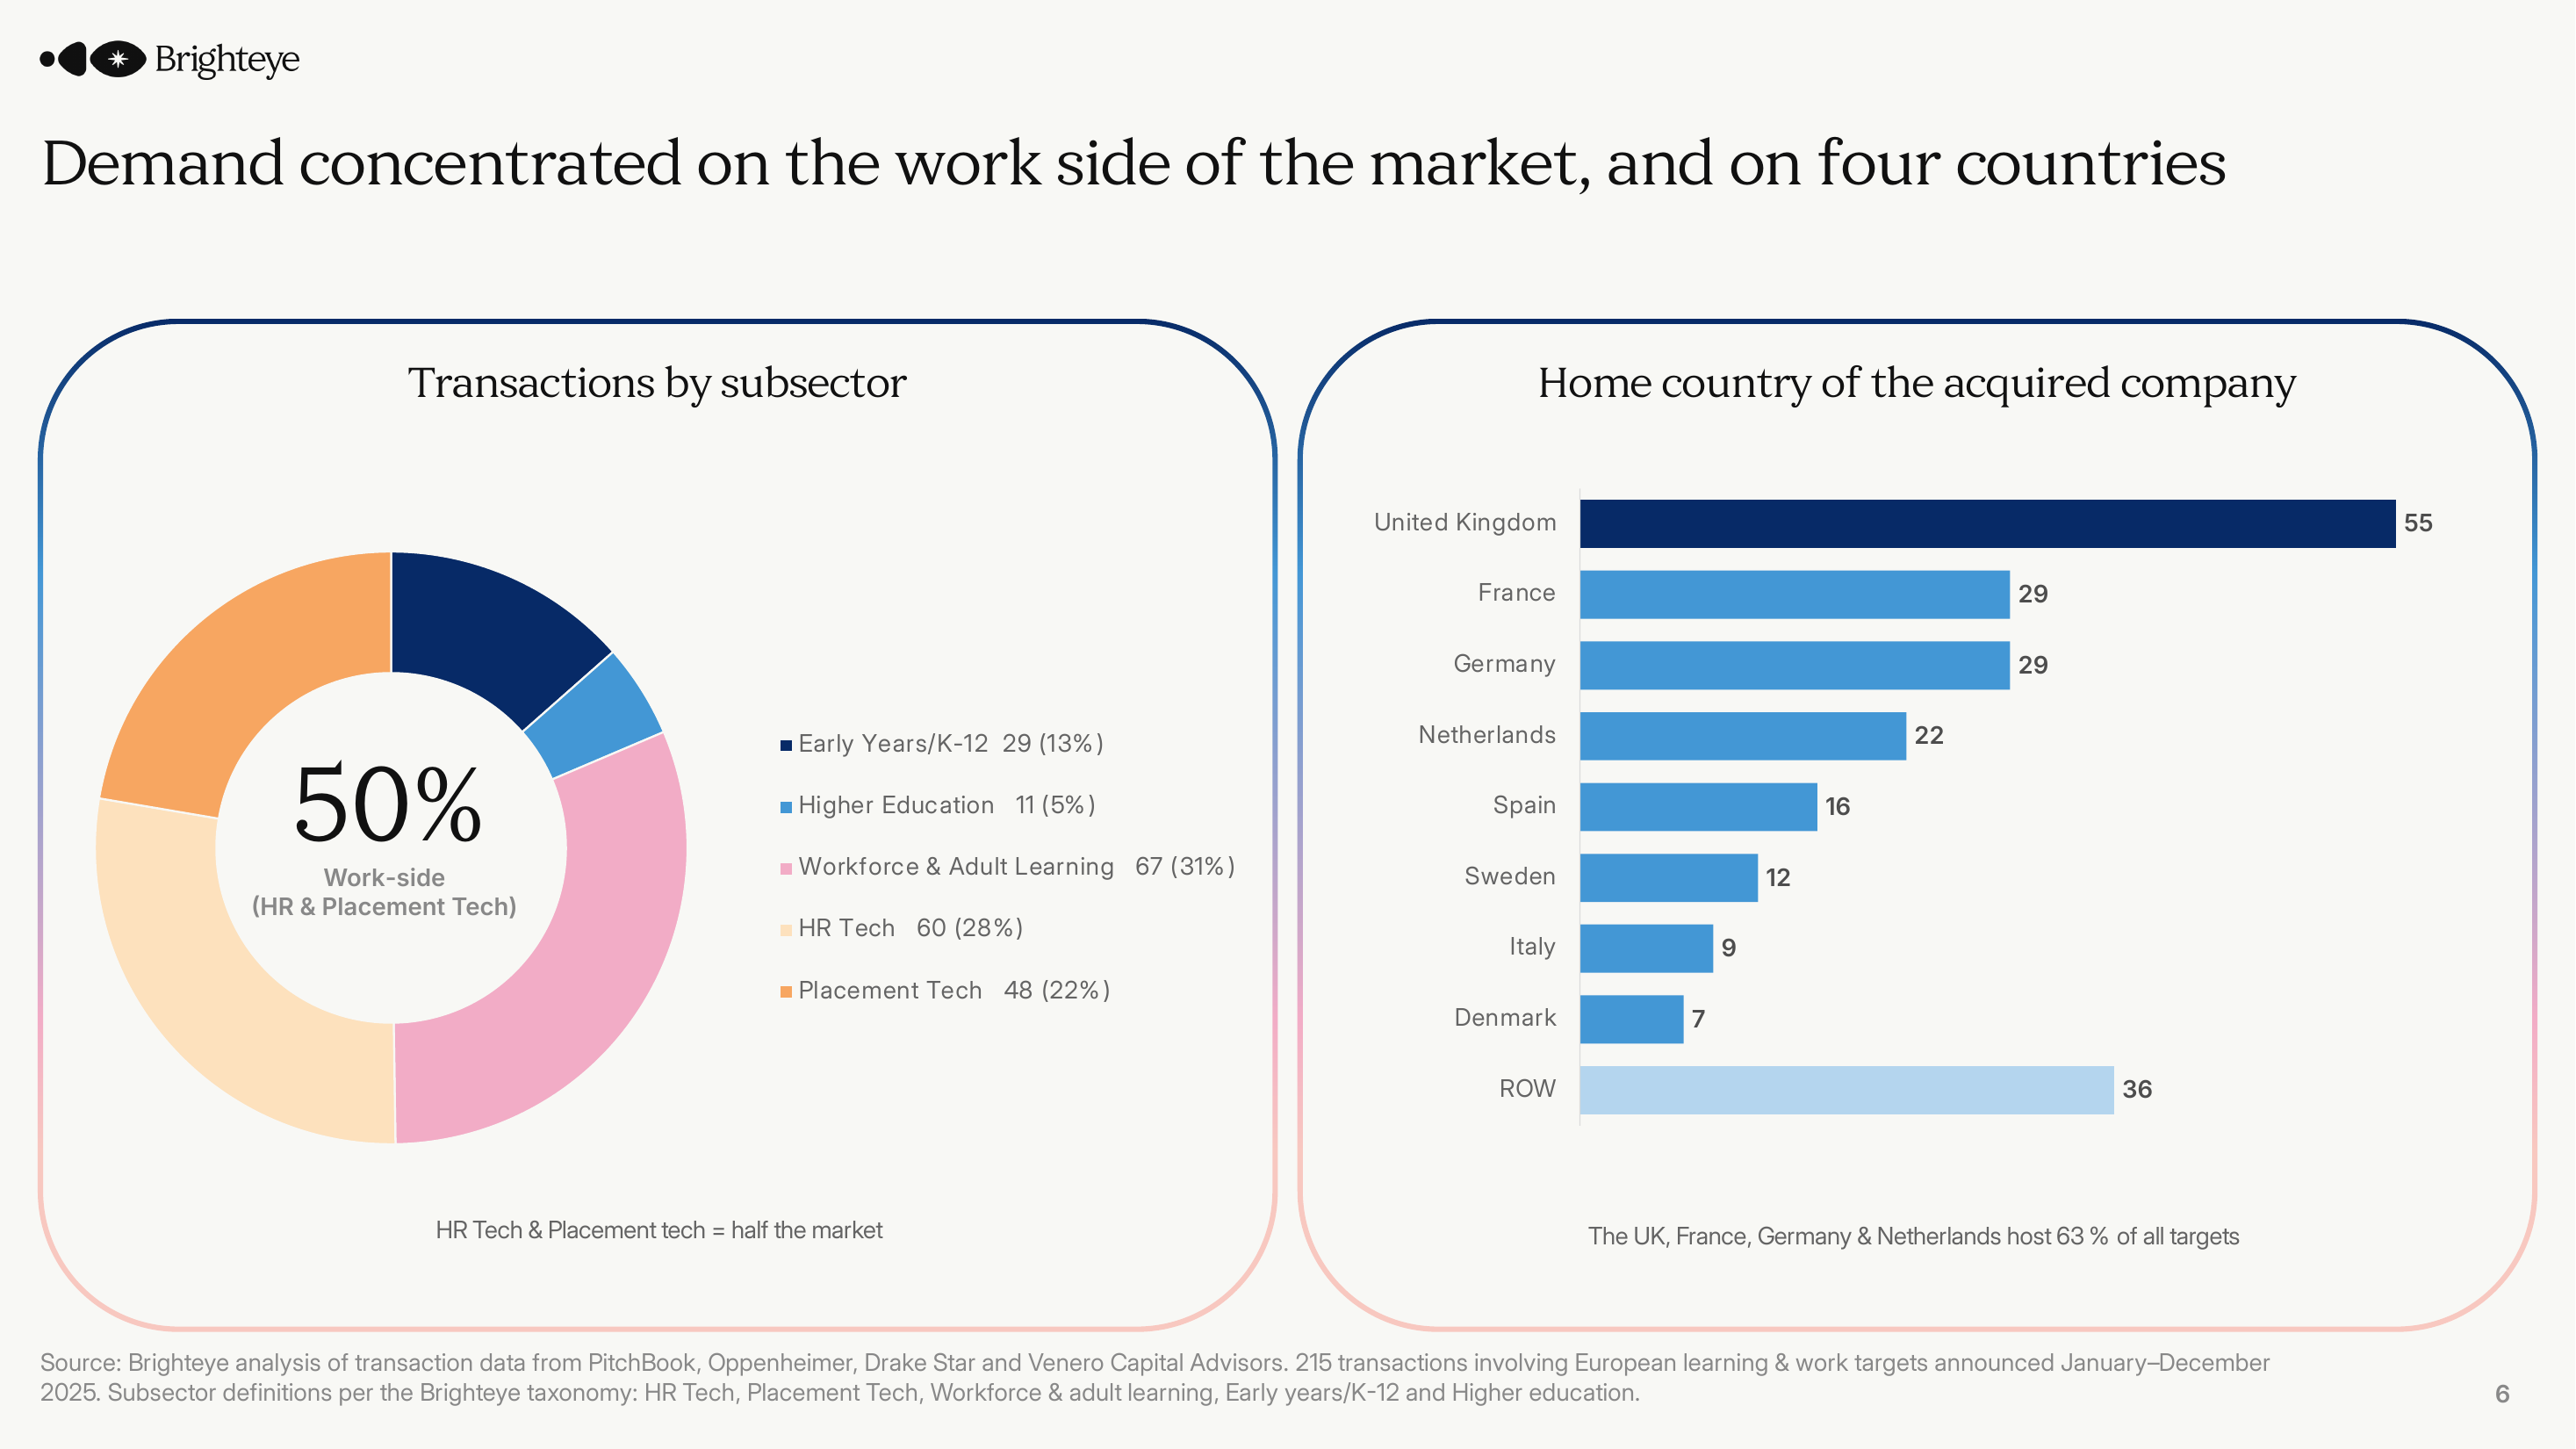
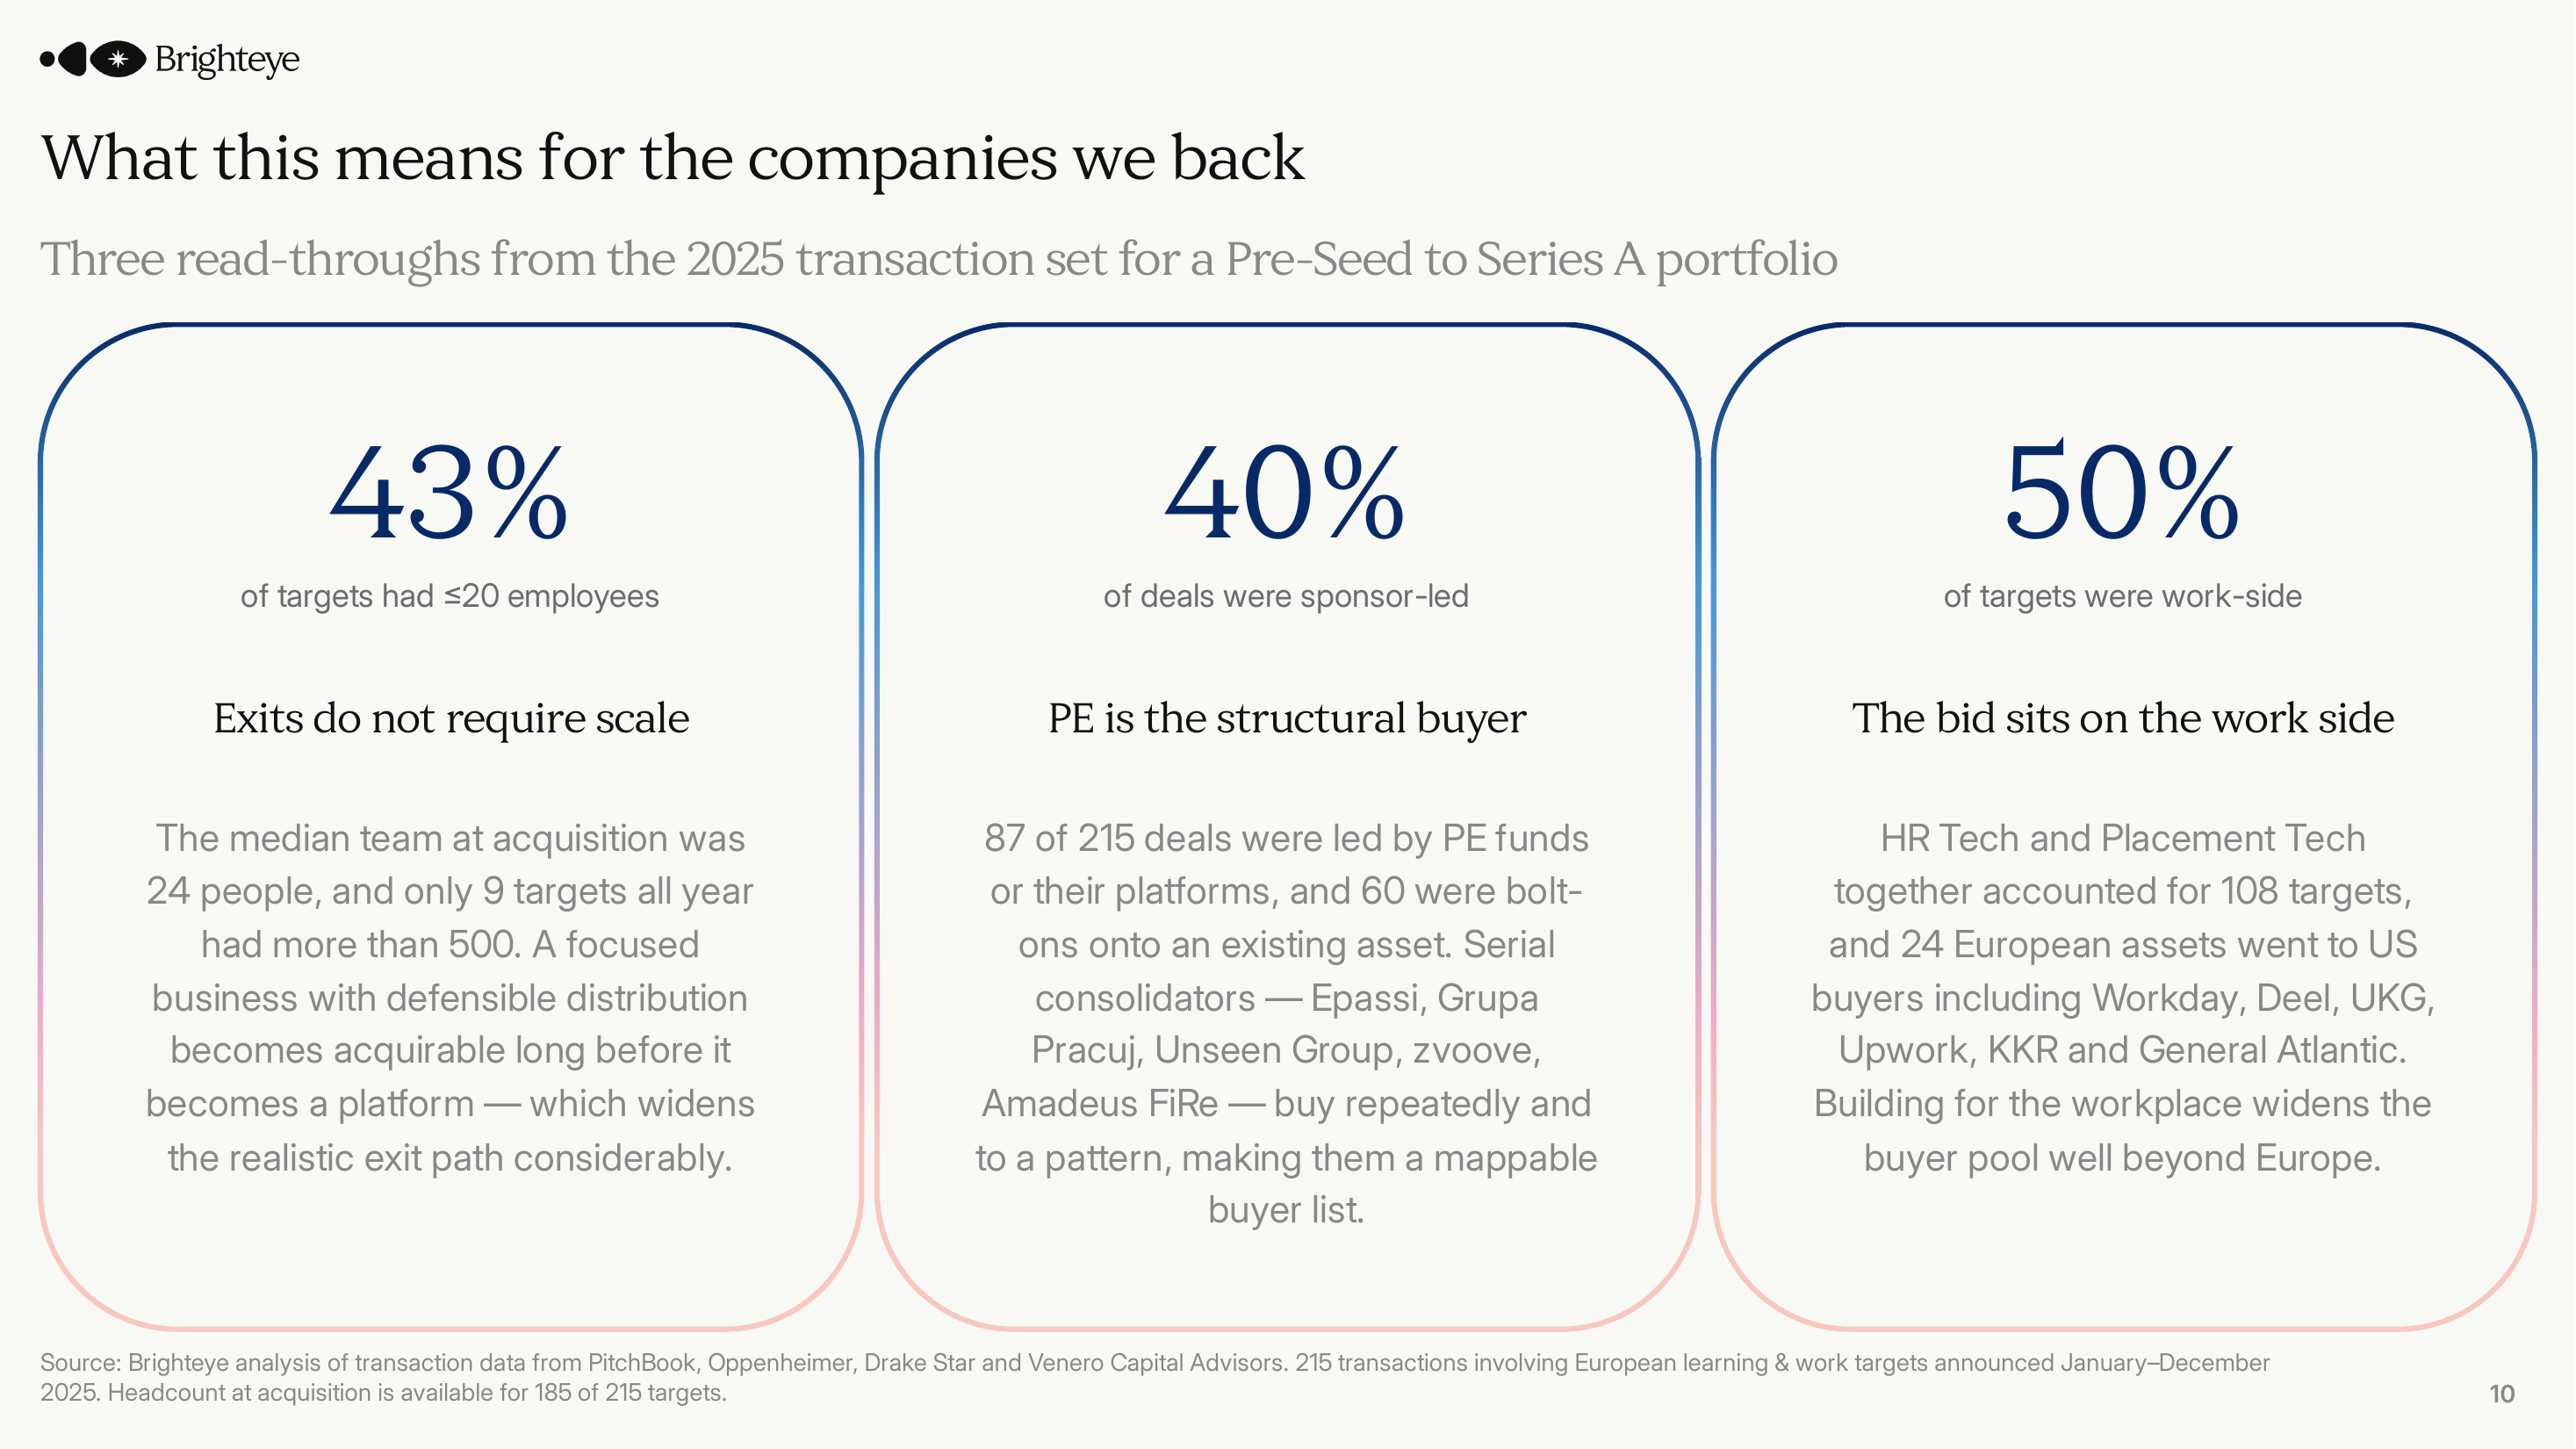
HR Tech and Placement Tech together accounted for 108 of the 215 targets, half the market. On a like-for-like basis, their share rose from 38% to 53%, while workforce and adult learning fell from 43% to 28%.
Geographically, the market was concentrated. The UK remained the deepest pool with 55 targets, ahead of France and Germany (29 each) and the Netherlands (22). Together, those four countries hosted 63% of all targets.
Exits do not require scale
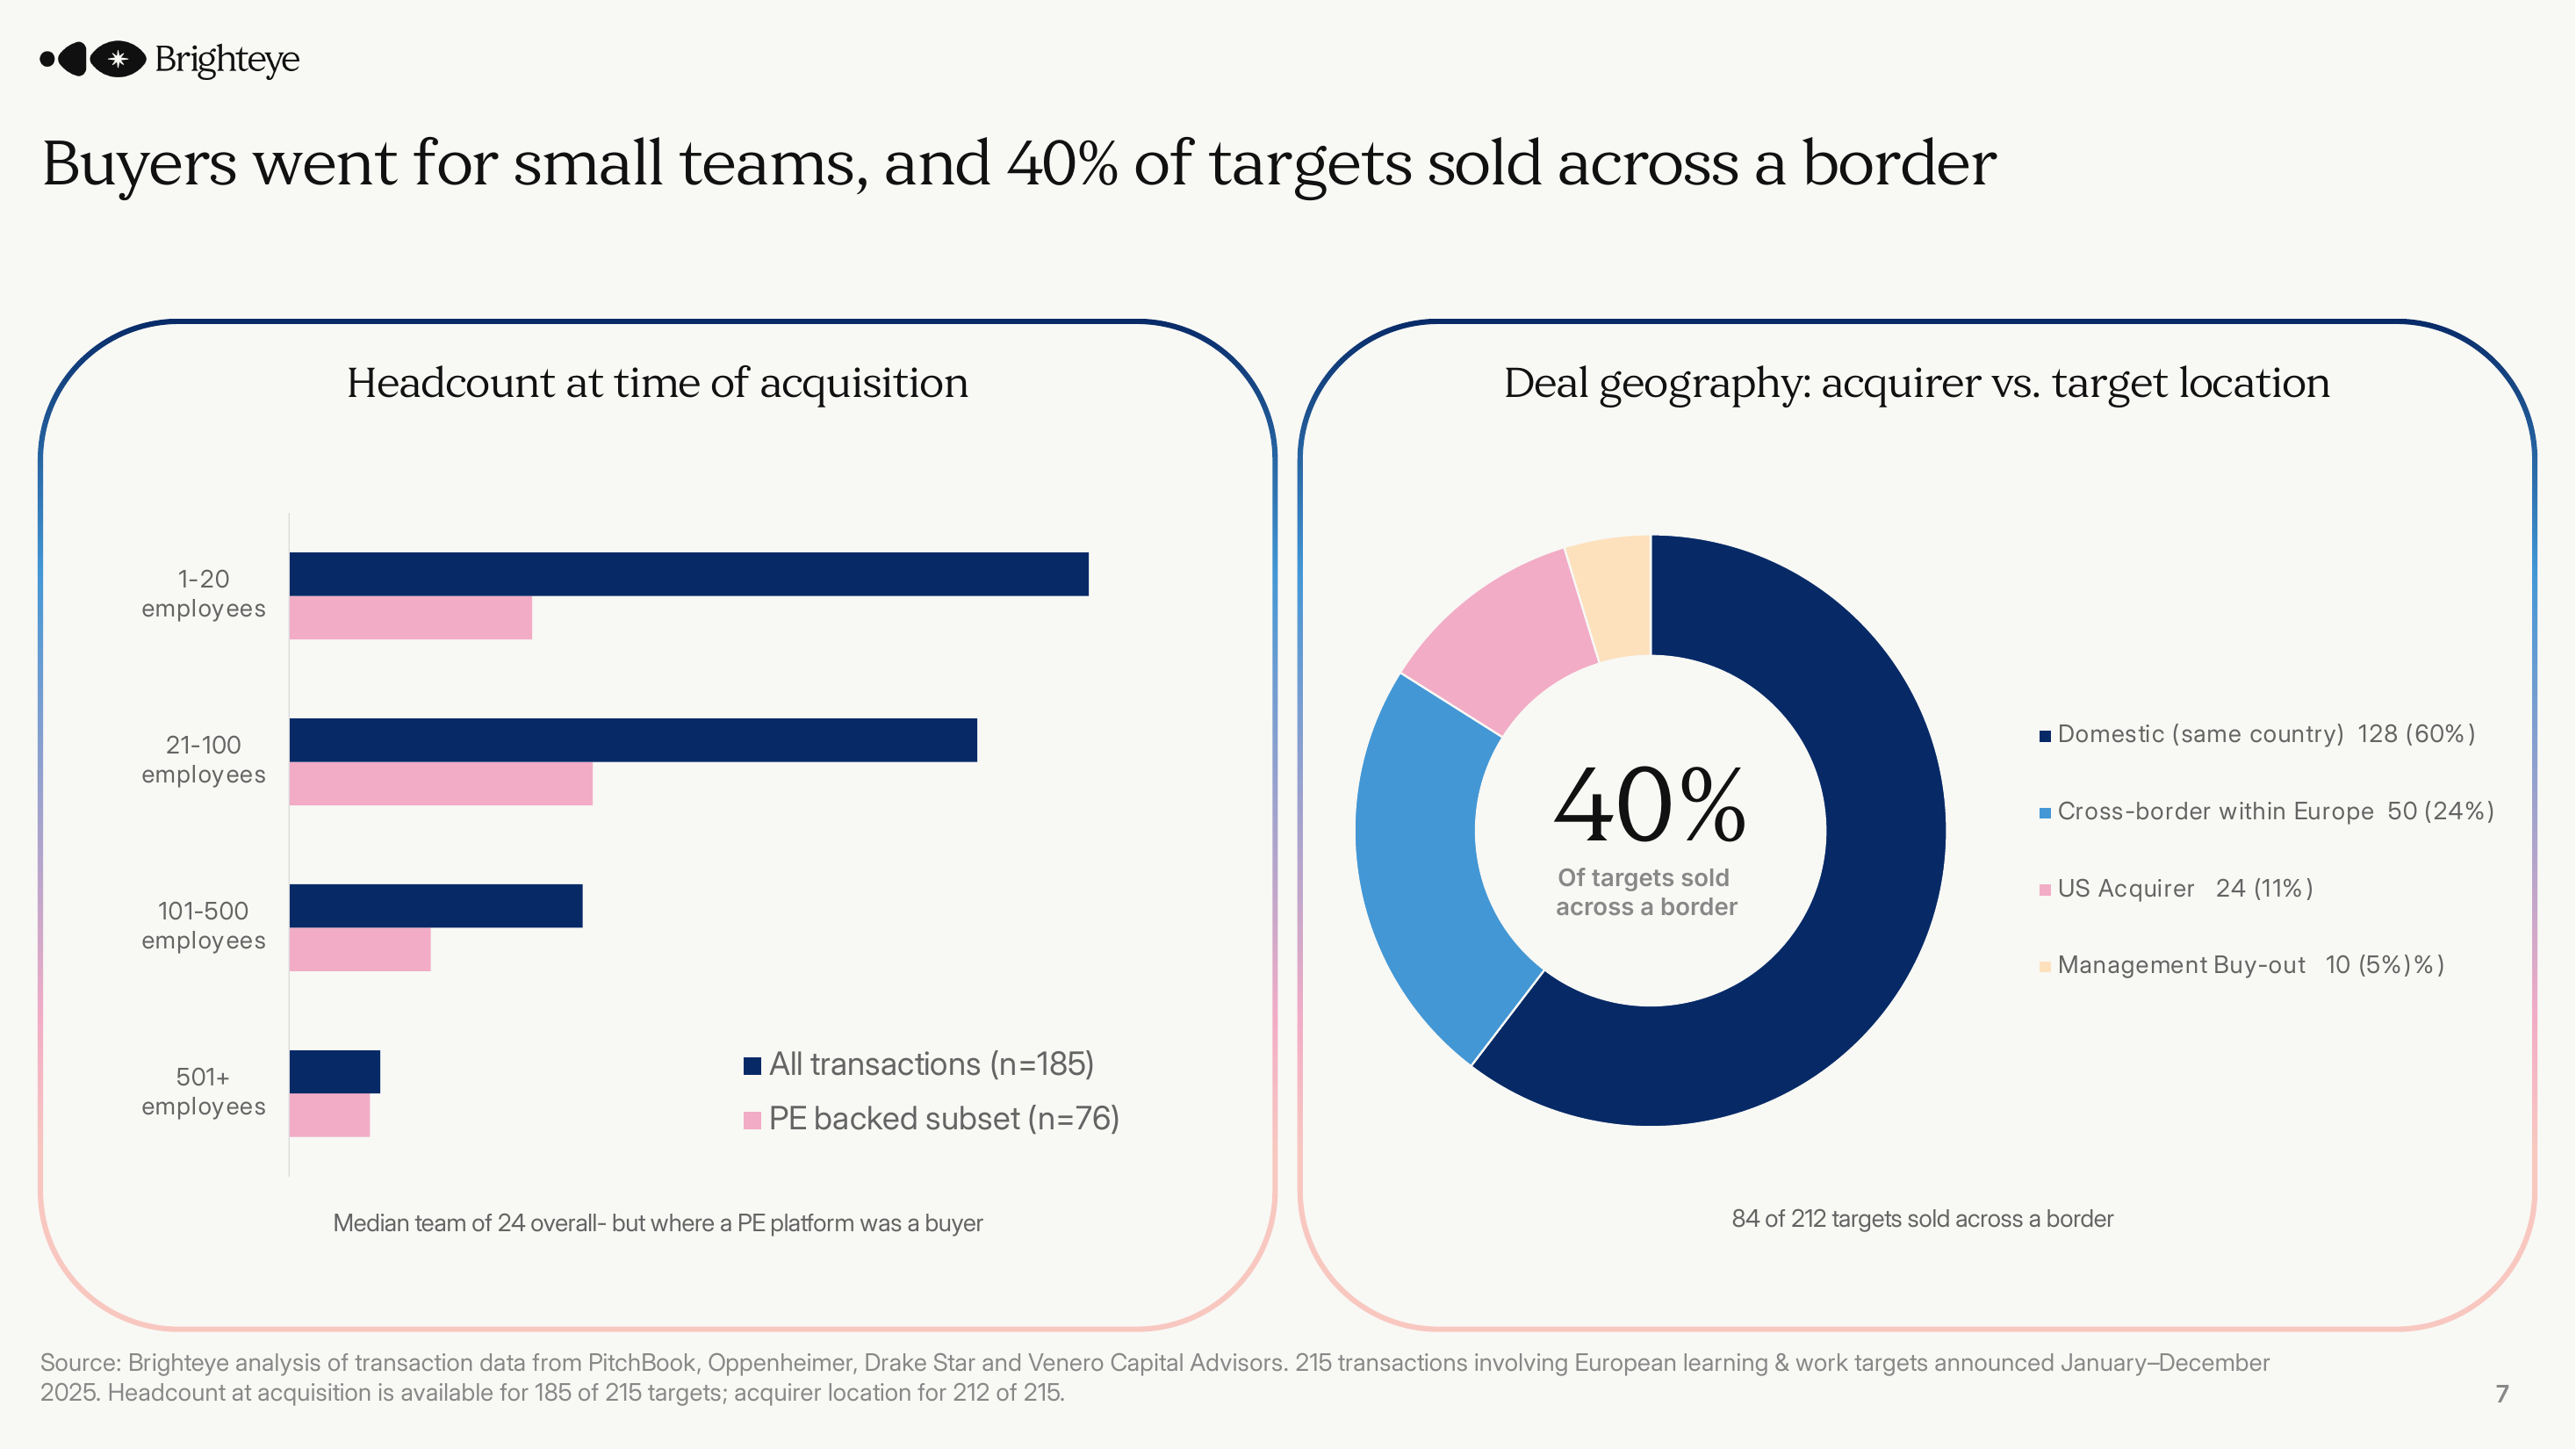
The median team at acquisition was 24 people. 43% of targets had 20 or fewer employees, and only nine had more than 500.
That points to a useful distinction between being acquirable and being a platform. Plenty of founders assume the first follows the second. In practice, a focused business with defensible distribution becomes acquirable long before it becomes a platform and that widens the realistic exit path considerably.
Buyers also looked well beyond their own borders. 40% of targets sold across a border, and 24 European companies went to US acquirers, including Workday, Deel, UKG and Upwork.
Private equity is the structural buyer, but nobody dominates
Private equity was behind 87 deals (40%) and 60 of those were bolt-ons onto an existing platform. Strategic and corporate buyers took a further 97 (45%), from Workday, Deel and UKG to Persol, Mercer and Penguin Random House. Only 30 deals (14%) had an Edtech or HR tech company as the acquirer. In-sector consolidation remains the exception rather than the rule.
The buyer set is also remarkably fragmented. 196 distinct acquirers completed the 209 deals where a buyer was named and nobody did more than two. For founders, the practical point is that the serial consolidators buy repeatedly and to a pattern. That makes them a buyer list you can map years before you need it.
What the numbers don't tell us
None of this means exits got easier across the board. Price stayed private: just 28 of 215 deals (13%) disclosed a value. The median disclosed value was $15m, against a mean of $168m pulled up by four deals above $1bn (The Key, Sana, LearningTechnologies Group and Arden University). On a like-for-like basis, the median disclosed value fell from $62m to $15m.
More deals, then, are not the same as bigger outcomes. Some of the activity among very small teams will be consolidation of sub-scale businesses rather than a founder win. And the shift away from adult learning is a signal worth taking seriously for companies whose model sits purely on the learning side, without a clear line into the workplace.
Where this leaves us
For the companies we back, the read-through is encouraging. The exit path in learning and work is wider, earlier and more international than the common view assumes, particularly for businesses built around the workplace. The question founders should be asking isn't only "how big do we need to get?" but "who is our buyer, and what would they need to see?"
If you're building in learning and work and thinking about these questions, we'd love to talk to you.
Download Brighteye's 2025 M&A Report
Source: Brighteye analysis oftransaction data from PitchBook, Oppenheimer, Drake Star and Venero CapitalAdvisors. 215 transactions involving European learning & work targetsannounced January–December 2025. 2024 comparisons are made on a Q1–Q3 basis.